Fiat Elpis · Meta earnings note 23

META: the Q3 2026 earnings cheat sheet

The revenue hurdle, the spending bill and the cash-flow questions. A two-page scorecard for the 21 October earnings release.

21 October 2026 4 min read

Fiat Elpis earnings scorecard

Strong advertising growth is only half the test. The other half is whether Meta can explain the spending bill and the cash returns it should produce.

The printable earnings scorecard

Meta reports Q3 2026 after the US market close on 21 October. The conference call starts at 16:30 ET / 20:30 UTC.

Download the two-page black-and-white PDF

Letter format, designed for a single duplex sheet. The full-resolution page images below open separately for easier reading.

The numbers to have in front of you

Q3 estimate snapshot supplied for this preview; not independently refreshed live
MetricSnapshotWhat matters
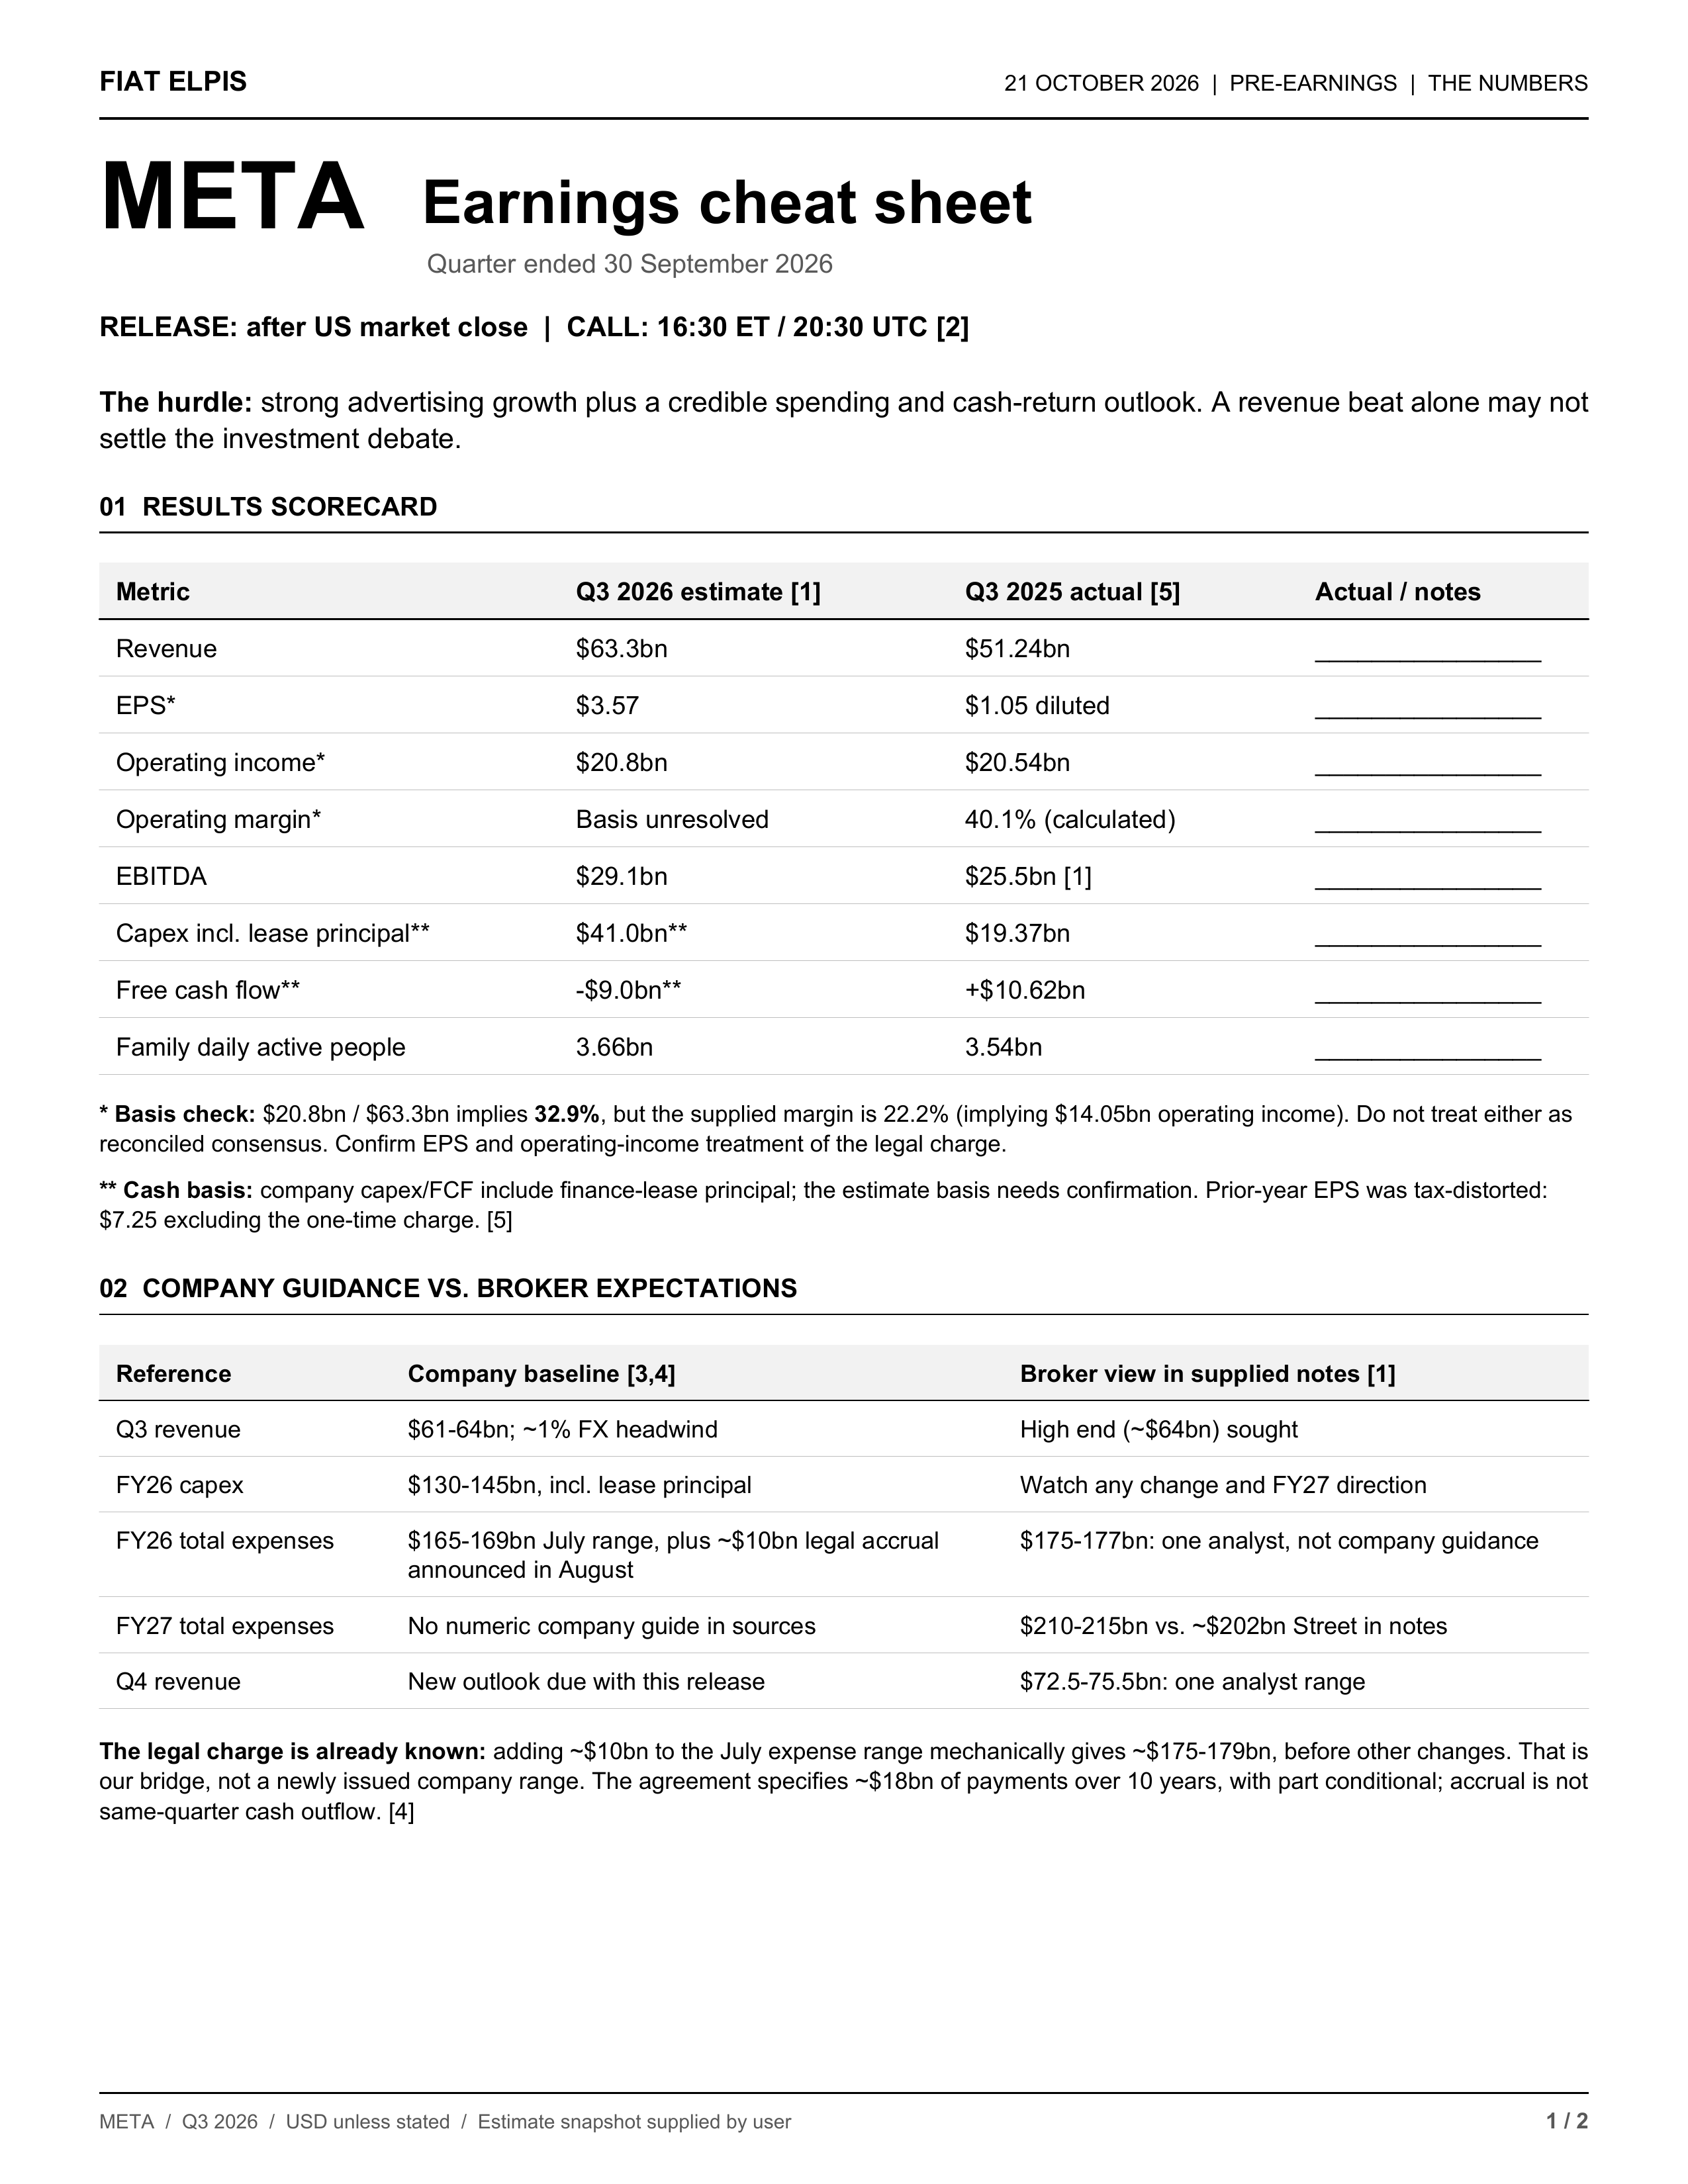
Revenue$63.3bnAgainst the company’s $61–64bn July guide.
Capex$41.0bnConfirm the estimate includes finance-lease principal.
Free cash flow−$9.0bnConfirm the same lease-payment basis as company FCF.
FY26 capex guide$130–145bnCompany baseline, including finance-lease principal.
FY27 expenses$210–215bnOne broker scenario in the supplied notes, versus ~$202bn Street; not company guidance.

Do not read the legal accrual as a new surprise. Meta announced an expected ~$10bn Q3 charge in August. Adding it to the July $165–169bn expense range gives a mechanical $175–179bn bridge before other changes, not a newly issued company range. The agreement specifies approximately $18bn of payments over ten years, with part conditional; accrual and immediate cash outflow are different.

The supplied operating-income and margin figures do not reconcile: $20.8bn divided by $63.3bn gives 32.9%, while the stated margin was 22.2%. The scorecard flags the conflict rather than presenting either as verified consensus. EPS and operating-income treatment of the legal charge also need confirmation.

Read both pages

META Q3 2026 earnings cheat sheet page one: results scorecard, company guidance and broker expectations, with legal-charge and accounting-basis notes.
Page 1 — results scorecard and guidance bridge.
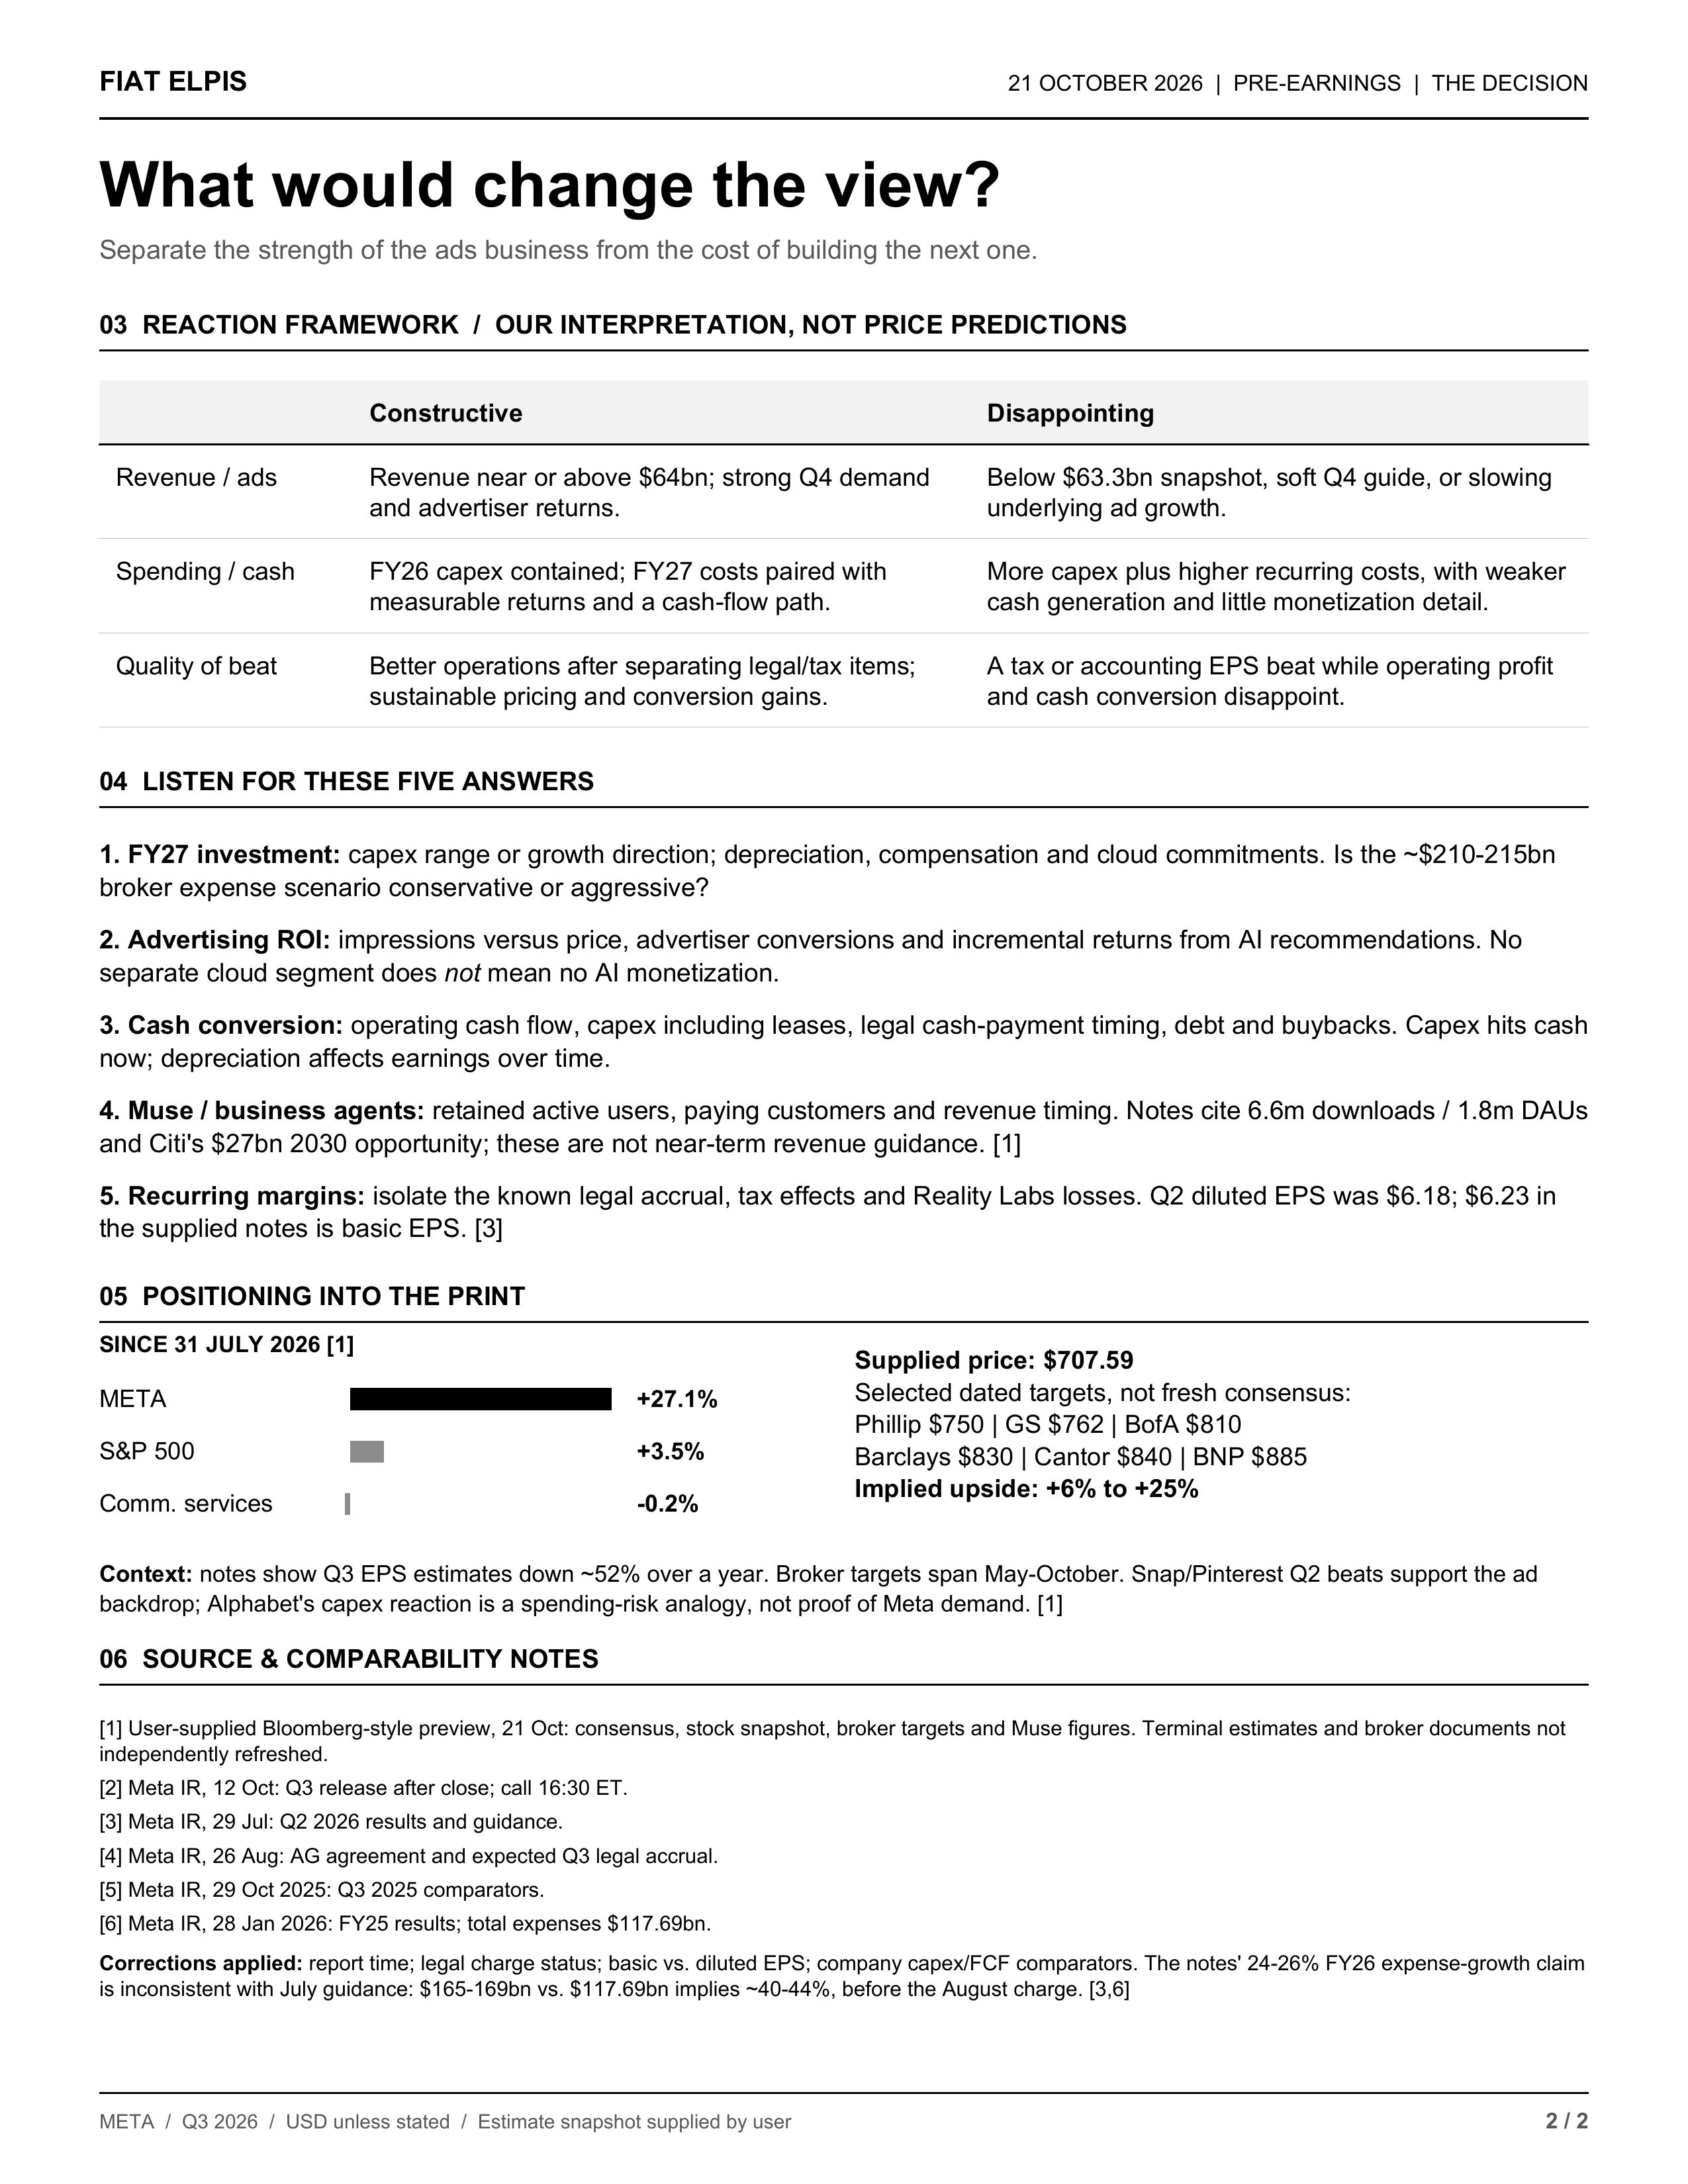
META Q3 2026 earnings cheat sheet page two: constructive and disappointing outcomes, five call questions, stock positioning and source notes.
Page 2 — reaction framework, call questions and positioning.

What would change the view?

Constructive: revenue near or above $64bn, strong Q4 advertiser demand, contained FY26 capex and a credible FY27 spending plan tied to measurable returns.

Disappointing: revenue below the $63.3bn snapshot, a soft Q4 outlook, or more capex and recurring costs with weaker cash generation and limited monetization detail.

Separate operating performance from legal and tax items. AI can already improve advertising returns without a separate cloud revenue line. Capex consumes cash now; depreciation affects earnings over time.

Sources and estimate basis

Company disclosures underpin the guidance, timing and historical corrections. Consensus, broker targets, stock performance and Muse figures come from the supplied 21 October preview and have not been independently refreshed from a live terminal. The framework is our interpretation, not a price prediction. This page is an archived pre-earnings preview.