Fiat Elpis · France & euro-area risk note 20
France Relief Trade: Long OATs, EUR and CAC 40
An imperfect budget compromise can be enough for a positioning-driven rebound.
Fiat Elpis tactical macro research
I recommend tactical longs in OATs, EUR and the CAC 40 into French budget relief. Forced bond selling and defensive positioning create room for an imperfect compromise to trigger a rebound. The trade needs improving expectations; debt stabilisation can come later.
The WSJ reported a 155bp OAT–Bund spread on Friday, approaching France’s 181bp euro-crisis peak, with leveraged carry trades being unwound. Goldman’s October 1 desk commentary reports heavy selling of French domestic stocks: it probably doesn’t take much good news to squeeze.
Its October 2 FX report places EUR in stretched-short territory.
Those observations support the relief thesis, although they do not establish crowded shorts across the entire CAC 40.1
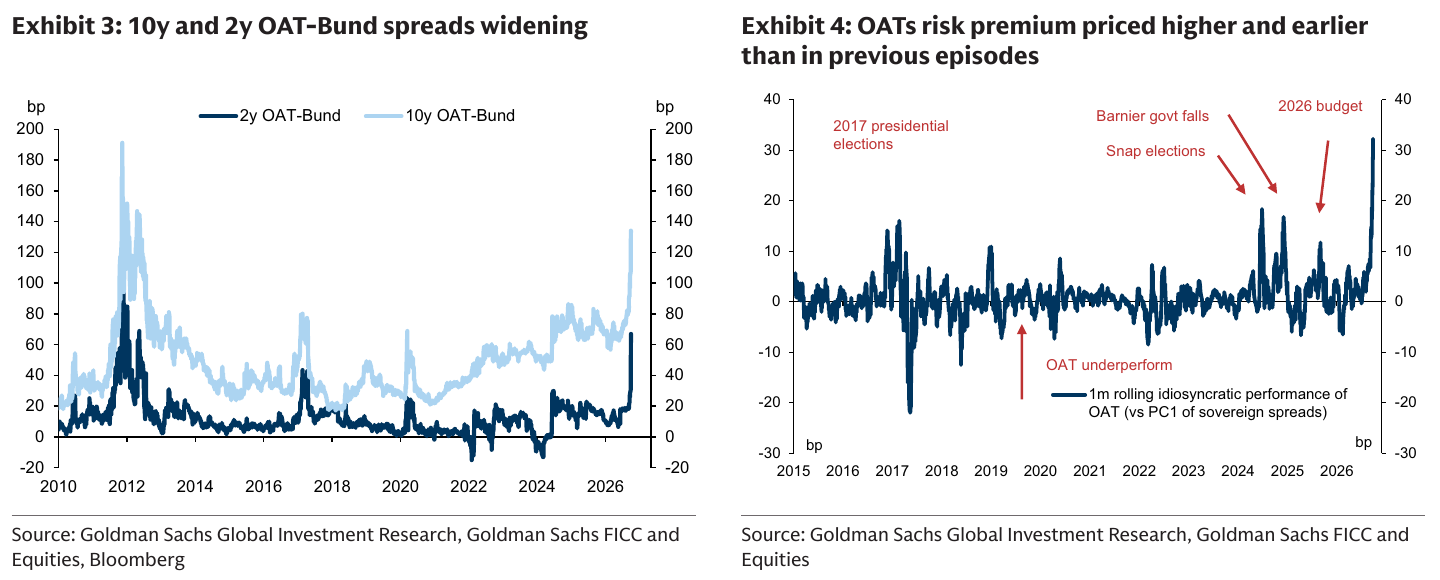
The proposed budget contains €54bn of total consolidation effort, including €43bn of new measures. It targets a deficit of 5% in 2027 versus 5.4% in 2026. The government estimates more than 6.5% without corrective action. That is meaningful containment, although the proposed path still leaves debt at 121.7% of GDP in 2027. The €54bn is an effort against a baseline, not an equivalent year-on-year deficit reduction. Government presentation; ING analysis.
| Sellside | View |
|---|---|
| BNP Paribas | Compromise likely; the government’s 1% growth assumption is credible. |
| ING | Modified budget likely; debt keeps rising and spread pressure persists. |
| Goldman Sachs2 | 0.6% growth in 2027; a 5.3% deficit forecast against the 5% target. |
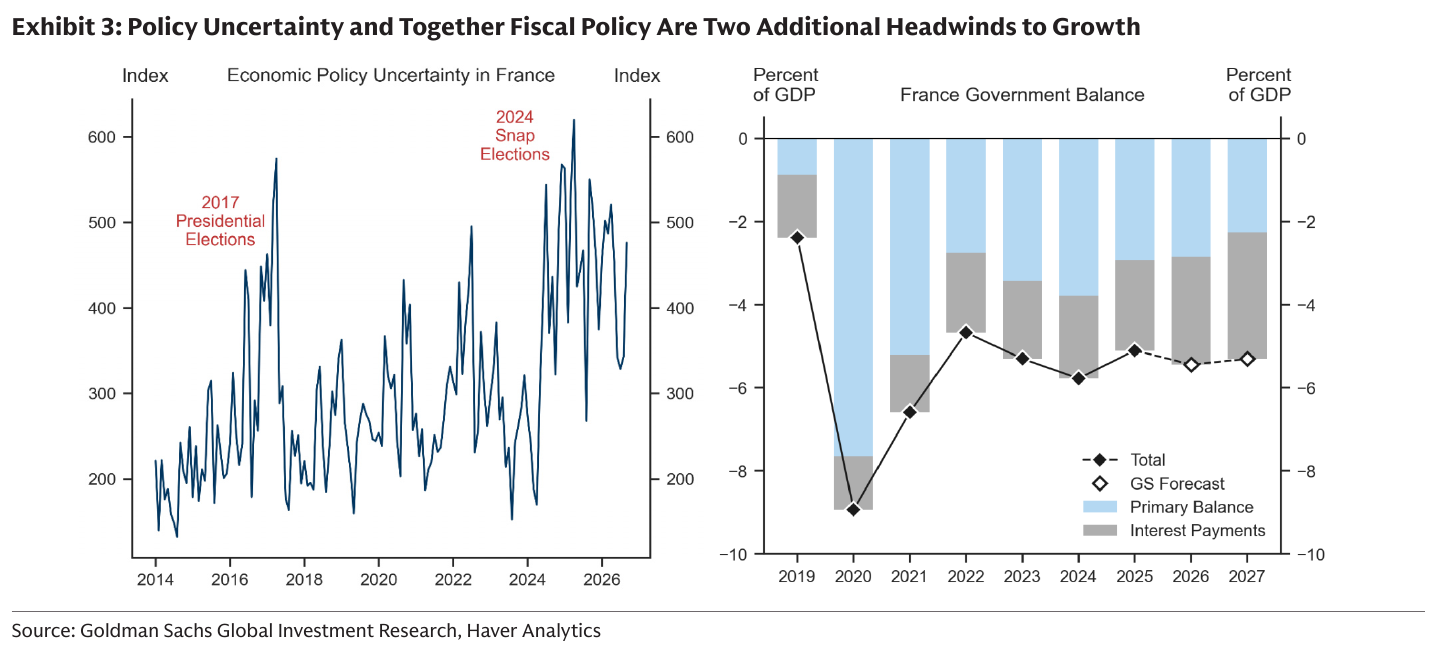
MUFG’s base case is a negotiated budget passed using Article 49.3. October 4 comments improve the political setup: LR rejects playing the censure game, while RN acknowledges censure could worsen the bond crisis. RN has not pledged non-censure. The market catalyst is credible progress toward passage, potentially before the final vote.
My trade inference: OATs express French risk-premium compression most directly. EUR adds positioning reversal as contagion eases. The CAC 40 adds equity upside if political uncertainty and financing pressure recede. OAT–Bund narrowing can accompany rising Bund yields, so outright OAT gains also depend on duration. The CAC 40’s global earnings exposure makes it a less direct France trade.
ECB support remains conditional. A QT pause is a strategist scenario. The trade can work without intervention; more dovish ECB pricing may help bonds while limiting EUR upside.
Watch: October 8 ECB accounts, October 13 budget debate and October 20 revenue vote. Censure, materially diluted savings or renewed forced selling would undermine the setup. I favour the relief basket while those risks recede. ECB calendar; MUFG timetable.